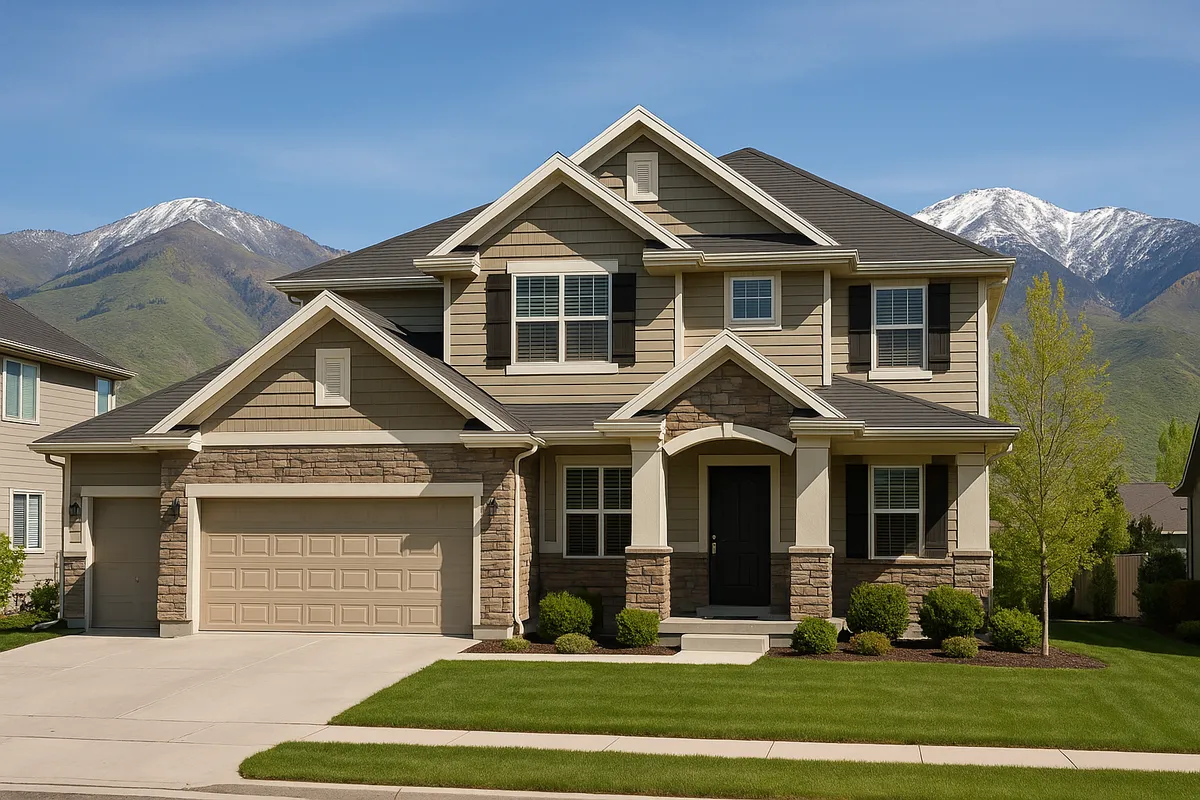
First-Time Homebuyer Guide to Farmington Utah 2026
First-Time Homebuyer Guide to Farmington Utah 2026
If you're a first-time homebuyer considering Farmington, Utah in 2026, this guide will walk you through exactly what to expect — from current market conditions and financing options to neighborhood selection and closing costs. Farmington sits in the heart of Davis County, offering quick access to Salt Lake City while maintaining a quieter, family-oriented community feel. The market here remains competitive, and first-time buyers who come prepared with the right knowledge consistently outperform those who don't. Whether you're relocating from out of state or moving up from a rental in the greater Salt Lake metro, understanding how Farmington works in 2026 is the first step toward making a sound purchase.
What Makes Farmington Utah a Good Place to Buy a Home in 2026?
Farmington has emerged as one of the more desirable communities along the Wasatch Front for buyers who want suburban livability without sacrificing convenience. Station Park, one of Utah's premier outdoor retail and entertainment destinations, anchors the city's commercial core and continues to drive economic activity and property values in surrounding neighborhoods. FrontRunner commuter rail access connects Farmington directly to downtown Salt Lake City and Ogden, which matters significantly to dual-income households evaluating where to plant roots.
From a school district standpoint, Davis County School District consistently ranks among the strongest in the state, a major factor for families entering homeownership for the first time. Farmington's parks, trail systems, and proximity to Farmington Bay Waterfowl Management Area give residents outdoor access that comparable price-point cities in Salt Lake County simply don't offer.
For a data-grounded view of current buyer activity and pricing trends in this market, the National Association of REALTORS® publishes monthly and quarterly housing statistics that give first-time buyers a reliable baseline for understanding how markets like Farmington fit into national trends.
What Are Home Prices Like in Farmington Utah for 2026?
Farmington home prices have held steady through the interest rate adjustments of the past two years, and inventory — while improved from the historic lows of 2021–2022 — remains tight in the entry-level and mid-range price bands where most first-time buyers compete. Expect median home prices in Farmington to range between the mid-$500,000s and high-$600,000s for single-family homes depending on location, lot size, and finish level. Townhomes and attached products offer an accessible entry point closer to the $400,000–$480,000 range, which aligns more practically with first-time buyer budgets in the current lending environment.
For a live snapshot of active listings and recent sales data, Zillow market data provides a useful public reference point, though working with a licensed agent who has access to the full MLS will give you a more accurate and timely picture.
David Supinger, CNE, CLHMS, Broker/Owner of HomeClick Real Estate and a Wall Street Journal Top 250 agent ranked #189 nationally, advises first-time buyers in Farmington to get pre-approved — not pre-qualified — before walking into their first showing. "In a market with limited inventory, sellers take offers from pre-approved buyers far more seriously," Supinger explains. "That single step can be the difference between getting a home and losing it."
What First-Time Homebuyer Programs Are Available in Utah in 2026?
Utah Housing Corporation (UHC) remains the primary state-level resource for first-time buyer assistance, offering down payment and closing cost assistance programs paired with competitive mortgage products. In 2026, UHC's FirstHome Loan program continues to serve buyers who meet income and purchase price limits, which are adjusted periodically based on county-level data. Davis County buyers should verify current UHC limits directly, as Farmington falls within a market tier that can shift year to year.
FHA loans remain the most widely used financing vehicle for first-time buyers nationally, requiring as little as 3.5 percent down for borrowers with qualifying credit scores. Conventional 97 products and Fannie Mae's HomeReady program also serve buyers with limited down payment funds while avoiding some of the long-term mortgage insurance costs associated with FHA financing. USDA loan eligibility in Farmington proper is generally limited due to the city's population density, but buyers open to nearby communities in eastern Davis County may find rural designation applies.
VA loans remain the most favorable product for eligible veterans and active-duty service members — zero down, no private mortgage insurance, and competitive rates. If you're a veteran considering Farmington, that benefit is worth using fully.
How Competitive Is the Farmington Utah Housing Market for First-Time Buyers?
Competition in Farmington is real but manageable for prepared buyers. Unlike the frenzied multiple-offer environments of 2020–2022, today's market allows for more measured decision-making while still rewarding buyers who move quickly on well-priced homes. Days on market for desirable properties in Farmington still trends short — often under two weeks for move-in-ready homes priced accurately.
First-time buyers should understand that their competition is not exclusively other first-timers. Move-up buyers with equity and investors with cash remain active in Davis County. This is where having an experienced advocate matters. David Supinger, MDM, CNE, CLHMS, brings over 33 years of negotiation experience and more than 1,300 homes sold to every transaction. His approach to offer strategy — including escalation clauses, inspection flexibility, and lender credibility letters — has helped first-time buyers compete effectively in markets far more heated than today's.
When you're ready to start your home search, explore the full buying process at vipluxuryteam.com/buying-a-home for a step-by-step overview tailored to this market.
What Should First-Time Buyers Know About Closing Costs in Utah?
Closing costs in Utah typically range from 2 to 4 percent of the purchase price for buyers, encompassing lender fees, title insurance, escrow charges, prepaid interest, homeowners insurance, and property tax reserves. On a $550,000 home, that's $11,000 to $22,000 in addition to your down payment — a figure that surprises many first-time buyers who focused exclusively on saving for the down payment itself.
Utah is an escrow state, and title companies handle the closing process rather than attorneys. Understanding what you're signing at closing is part of the preparation every first-time buyer should undertake well before the day arrives. Your lender is required to provide a Loan Estimate within three days of application and a Closing Disclosure at least three business days before closing — read both carefully and ask questions.
Seller-paid closing costs, or seller concessions, are negotiable in many transactions. In a market where some sellers are sitting on longer days-on-market, there is often room to negotiate a credit toward closing costs as part of the offer structure. David Supinger's designation as a Certified Negotiation Expert (CNE) specifically applies here — knowing how to structure requests for concessions without weakening your offer position is a skill that comes from experience, not intuition.
Is Now a Good Time to Buy a Home in Farmington Utah?
The honest answer is: it depends on your personal financial readiness more than on the market. Buyers who are financially prepared — stable income, manageable debt load, sufficient reserves, and a multi-year planning horizon — consistently do well in Farmington regardless of the interest rate environment at the moment of purchase. Trying to time the market perfectly is a strategy that costs more in missed equity and rental payments than most buyers realize.
If you're considering selling a property elsewhere to fund your Farmington purchase, review the current seller's playbook at vipluxuryteam.com/selling-your-home before making any decisions about sequencing your transaction.
To talk through your specific situation with someone who knows this market at a granular level, call David Supinger, Wall Street Journal Top 250 agent and Broker/Owner of HomeClick Real Estate, directly at 801-698-2526. With 33 years of experience and over 1,300 homes sold across Davis County and the greater Salt Lake metro, he brings the kind of grounded perspective that first-time buyers need most when the stakes are highest.
Frequently Asked Questions: First-Time Homebuyer Farmington Utah 2026
How much do I need for a down payment to buy a home in Farmington Utah?
Most first-time buyers in Farmington use FHA financing with a minimum 3.5 percent down payment, or conventional programs requiring as little as 3 percent for qualifying buyers. On a $550,000 purchase, that means roughly $16,500 to $19,250 at minimum. Utah Housing Corporation programs may also provide down payment assistance for income-qualifying buyers, reducing the out-of-pocket requirement further.
What credit score do I need to buy a home in Farmington Utah in 2026?
FHA loans typically require a minimum credit score of 580 for the 3.5 percent down option, while conventional loans generally require 620 or higher for approval. Scores above 740 unlock the most favorable interest rates. If your score needs improvement, most lenders can provide a credit action plan — even a 30 to 60-day improvement effort can meaningfully affect your rate.
How long does it take to buy a home in Farmington Utah?
From accepted offer to closing, most Farmington transactions close in 25 to 40 days depending on loan type, inspection timelines, and any negotiated repair resolutions. Getting your pre-approval in place before you begin searching eliminates the most common delay. The full process from initial search to closing keys in hand typically spans four to eight weeks for prepared buyers.
Are there good schools near homes for sale in Farmington Utah?
Yes. Farmington is served by Davis County School District, which consistently ranks among the top performing districts in Utah. Farmington High School, Viewmont High School, and several well-regarded elementary and junior high campuses serve neighborhoods across the city. School boundaries should always be verified directly with Davis County School District before making a purchase decision based on school assignment.
Do I need a real estate agent to buy a home in Farmington Utah?
While not legally required, working with a licensed buyer's agent in Utah costs you nothing as the buyer — the seller's proceeds fund agent compensation. An experienced agent provides access to full MLS data, negotiation expertise, contract knowledge, and local market insight that no online portal replicates. In a competitive market, attempting to navigate a transaction without representation is a significant disadvantage for first-time buyers.
About David Supinger
David Supinger is a Certified Luxury Home Marketing Specialist (CLHMS), Resort and Second Home Property Specialist (RSPS), and Certified Negotiation Expert (CNE). Wall Street Journal Top 250 agent. Broker/Owner HomeClick Real Estate, 33+ years, 1,300+ homes sold. 801-698-2526 | vipluxuryteam.com